Hidden deep within last week’s UK Budget was a plan by the Chancellor to close a National Insurance loophole which allowed those who have previously lived in the UK to – relatively cheaply – qualify for a full UK state pension upon retirement
From 6 April 2026, individuals living or working outside the UK will no longer be allowed to pay the cheaper Class 2 voluntary National Insurance Contributions (around £170 per year) to preserve or build up their entitlement to the UK state pension. Instead, if you wish to continue paying, you’ll now be forced to use Class 3 voluntary contributions (around £930 a year).
On top of that, the UK residency/contribution threshold is being raised. To qualify to pay voluntary NICs from abroad, you must now have either lived in the UK for at least ten continuous years, or have at least ten qualifying years of UK NICs under your belt before moving abroad.
Thankfully, the changes do not apply retrospectively, meaning any contributions made to date remain unaffected.
Those who took advantage of the buy-back scheme earlier this year to fill in missing years need to now do some maths to see whether it is going to be worth continuing to contribute.
How it will impact everyone will depend upon how many years are left in an individual’s records before they reach 35 years of contributions. If you log on to your HMRC pension portal, you will see how many more years you will need to contribute to get to the full £230 a week. You can then do some simple maths to determine how long it will take you to get into profit if you choose to buy the missing years at the higher rate.
For example: if you have 25 years worth of contributions to your name, the system may tell you your pension pot entitles you to £175 a week once you retire. If you wanted to reach the maximum £230 a week pension, you need 35 years’ worth of contributions, meaning you are ten years short. For the sake of the calculation, we will assume that the contribution rate stays the same (which it will not). It means you are going to have to pay ten x £930 to reach the full pension, meaning you will have paid an extra £9,300. That will then entitle you to the extra £55 per week. But if you divide your £9,300 by £55, it means you will need to draw you pension for at least 169 weeks (or three years and three months) before you earn your £9,300 back and start making profit. Interestingly, the closer you are to the 35 years, the less attractive the proposition becomes to buy any more back.
So, log on to your account and work out how much more you will need to pay to make the full pension, and then divide that by the extra pension it will give you to see how many weeks it will take for you to earn that money back. You can then decide whether you think it will be worth it.
If in any doubt, seek some proper financial advice.
 Storm-proof your home – and your insurance
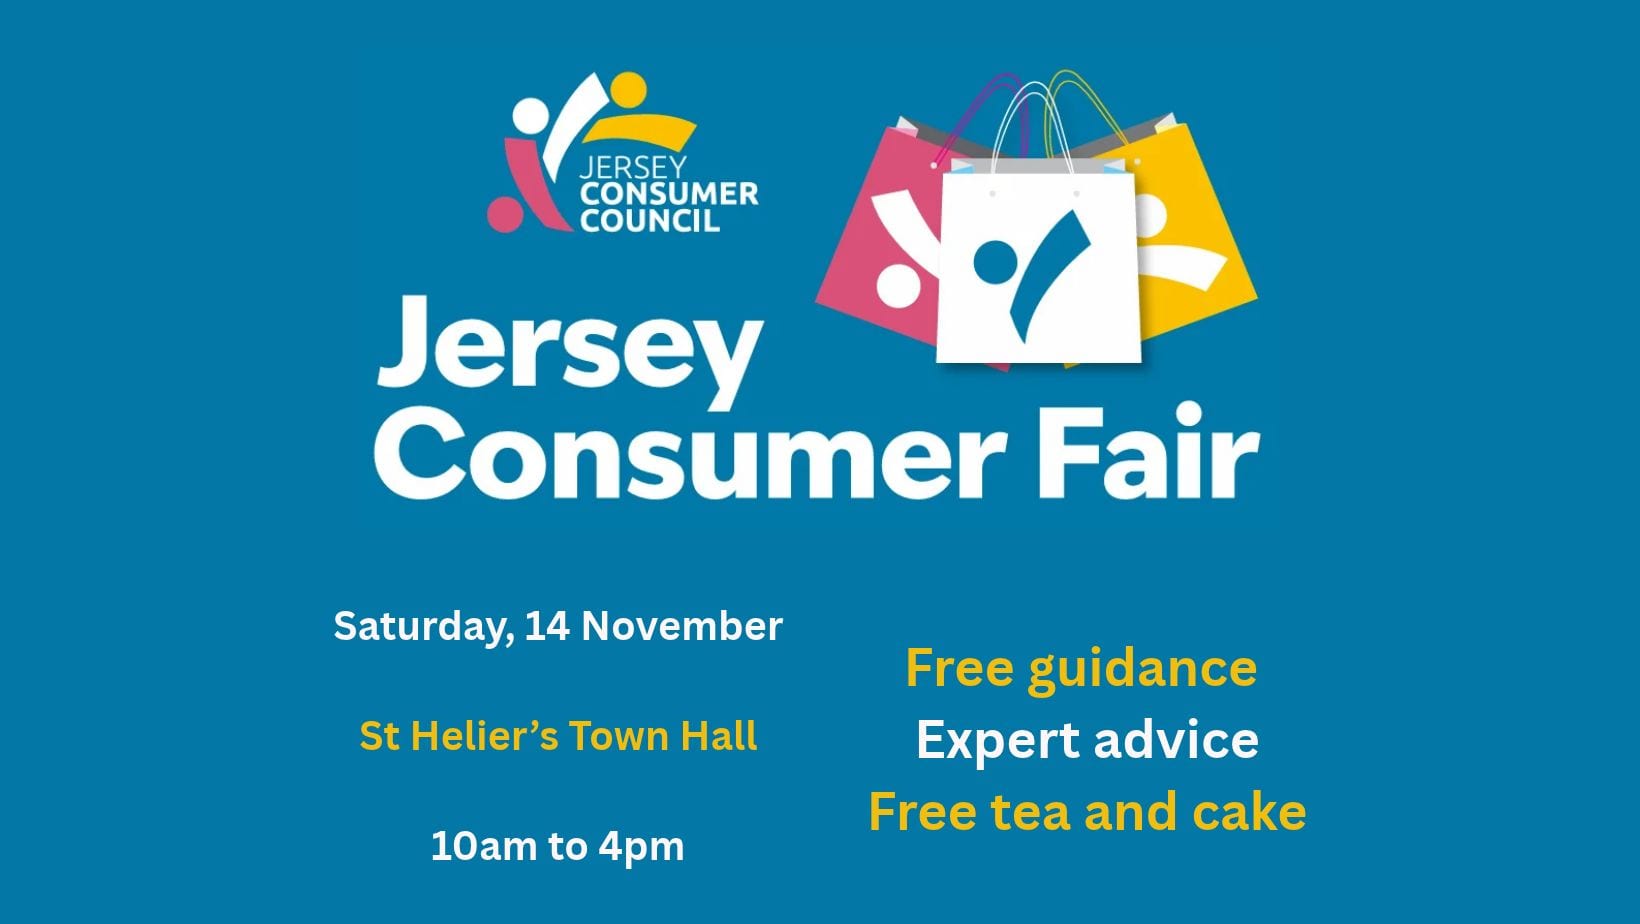 The Jersey Consumer Fair is back!
 Don’t let Halloween turn scary: safety tips for costumes, toys and accessories
 Spreading the cost of Christmas: why now is the time to start
 Are Jersey residents covered by Saga travel insurance?
 Amazon 'Prime Big Deal Days' – Are there genuine bargains to be found?